A surprise scooter repair or a delayed client payment can turn a long-term investment into money you suddenly need to withdraw. That is why saving and investing work better as separate decisions, each with a clear purpose. Before comparing interest rates or funds, decide when the money might be needed.
Match money to its purpose
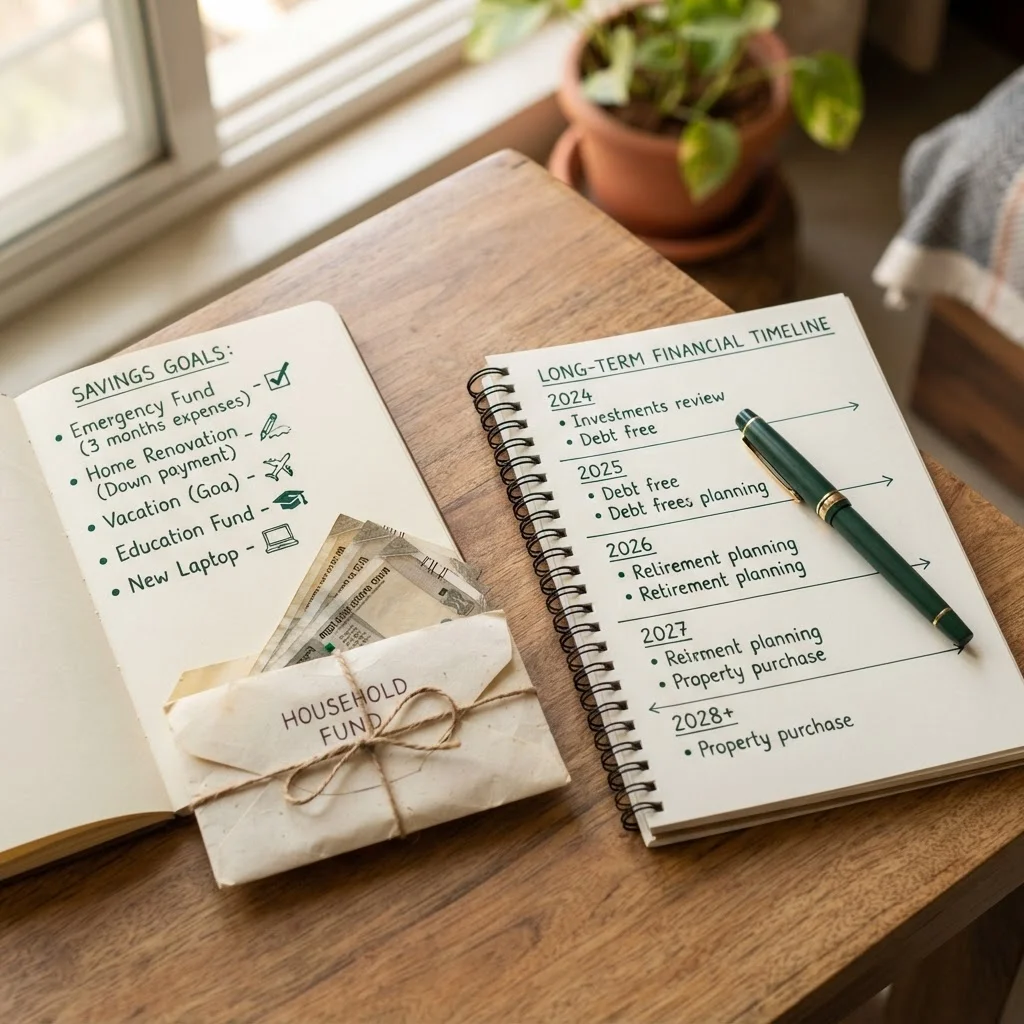
Savings are for near-term needs and unexpected expenses: rent, school costs, a medical bill, or a temporary gap in income. Keeping this money accessible can matter more than seeking a higher return, especially if withdrawing an investment at the wrong time would disrupt your plans.
Investing is generally for goals that can withstand ups and downs over a longer period, such as building wealth for a future milestone. The right time horizon depends on your circumstances, and investments can lose value. Money needed soon usually deserves a different approach from money you can leave untouched.
Build a simple order
Start by listing essential monthly expenses and the bills that arrive irregularly, such as annual insurance payments or school fees. Set aside what you can for a readily accessible reserve, then review costly debt and upcoming commitments before deciding how much is available for longer-term investing.
A separate savings account or clearly labelled account can help prevent everyday spending from blurring the purpose of your reserve. Once the near-term plan is clearer, compare investment options by their risks, costs, and fit with your goal rather than by recent performance alone.
Review when life changes
A new job, a move, or a change in family responsibilities can alter how much cash you need close at hand. Review the plan when those changes happen, not because a market headline has made you anxious. The practical takeaway is simple: name the job of each sum before choosing where to keep it.